

Your really helpful home application guide
Throughout this guide, we'll provide you with helpful tips on how to avoid delays for your client’s application.
-
Pre submission
-
Submission

-
Post submission
-
Assessment

-
Post assessment

This section sets out key steps you need to take in preparing to submit an application to us.
Scenarios
Looking for a solution for your client’s scenario? Talk to your BDM to see if we can help. Alternatively, you can send us the details using the Scenario Form on our Adviser Hub.
In our world, there are always exceptions. For scenarios that don’t fit our standard guidelines, you can speak to your BDM.
Product Selector
Know where your client stands, fast.
To see if we can help, jump online, answer a simple set of questions about your client’s current situation, and we may be able to provide an indicative offer.
You are required to obtain and keep your client's consent to obtaining a credit report via an access seeker request at the start of the Product Selector process. But don’t worry, this won’t impact their credit score.
If the information provided in the Product Selector is correct and verified when an application is submitted, then the indicative offer interest rate and fees will be valid*. It’s your 24/7 digital BDM.
Upfront valuations
Upfront valuation fees are at cost.
Check out our current home loan fees on the adviser hub.
Important: Before using Product Selector, you must ensure you have received and retained your customer’s written consent to complete an access seeker request. You must provide a copy of this consent if requested by Pepper Money. Applications are subject to responsible lending, credit assessment, eligibility criteria and lending limits. *An indicative offer is not a formal approval for a loan and financial commitments must not be entered into based on it. It is not a suggestion or recommendation of any particular loan product. It is a guide only based on the limited information provided and the credit score obtained. The actual interest rate and fees will depend on the borrower’s circumstances and the information verified when a formal loan application is submitted and assessed. If there are two or more applicants, the circumstances of the other applicants may affect Pepper Money’s decision regarding any formal loan application.
Before submitting the loan application, ensure you have completed all required application forms and gathered all supporting documentation.
Send the application pack to your BDM or advisersupport@peppermoney.co.nz. Once received, the application will be reviewed and prepared for credit assessment, with any additional information requested as needed.
Confirming your client’s identity
Your client will need to provide one form of photo ID with their application, such as:
- A current New Zealand passport (preferred option)
- A current New Zealand driver’s licence
- A current New Zealand proof of age card
- A current Overseas passport
Their solicitor will complete the required identity verification.
Supporting documents
Make sure you’ve included all the minimum document requirements needed to assess your client's application. Before submitting your client’s application, check the required documents checklist to make sure you’ve included everything we need to assess their application.
Always add your adviser notes:
Tell us your client’s story and what they’re looking to do, so we can get a good understanding of who they are and why this deal is important to them. We’ve included some prompts to help you get started.
Your client's situation
- Details about the scenario
- Reason for default/late payments (if applicable)
- How does this loan put them in a better position?
- What are they looking to do with the cash out (if applicable)
About the clients, company or trust
- The client's/company's background.
- The transaction and what they would like to do
- How did they start the business?
- Where do they trade?
- Office locations? If no office, why?
Your client's income as an employee
- Where do they work/what do they do?
- Are they full-time, part-time, or casual?
- How many hours do they work a week?
- Do they get paid any allowances, overtime, or bonuses, etc?
- How is their income calculated?
This section sets out how to track your client's application from submission to settlement.
Tracking the progress of your client's application
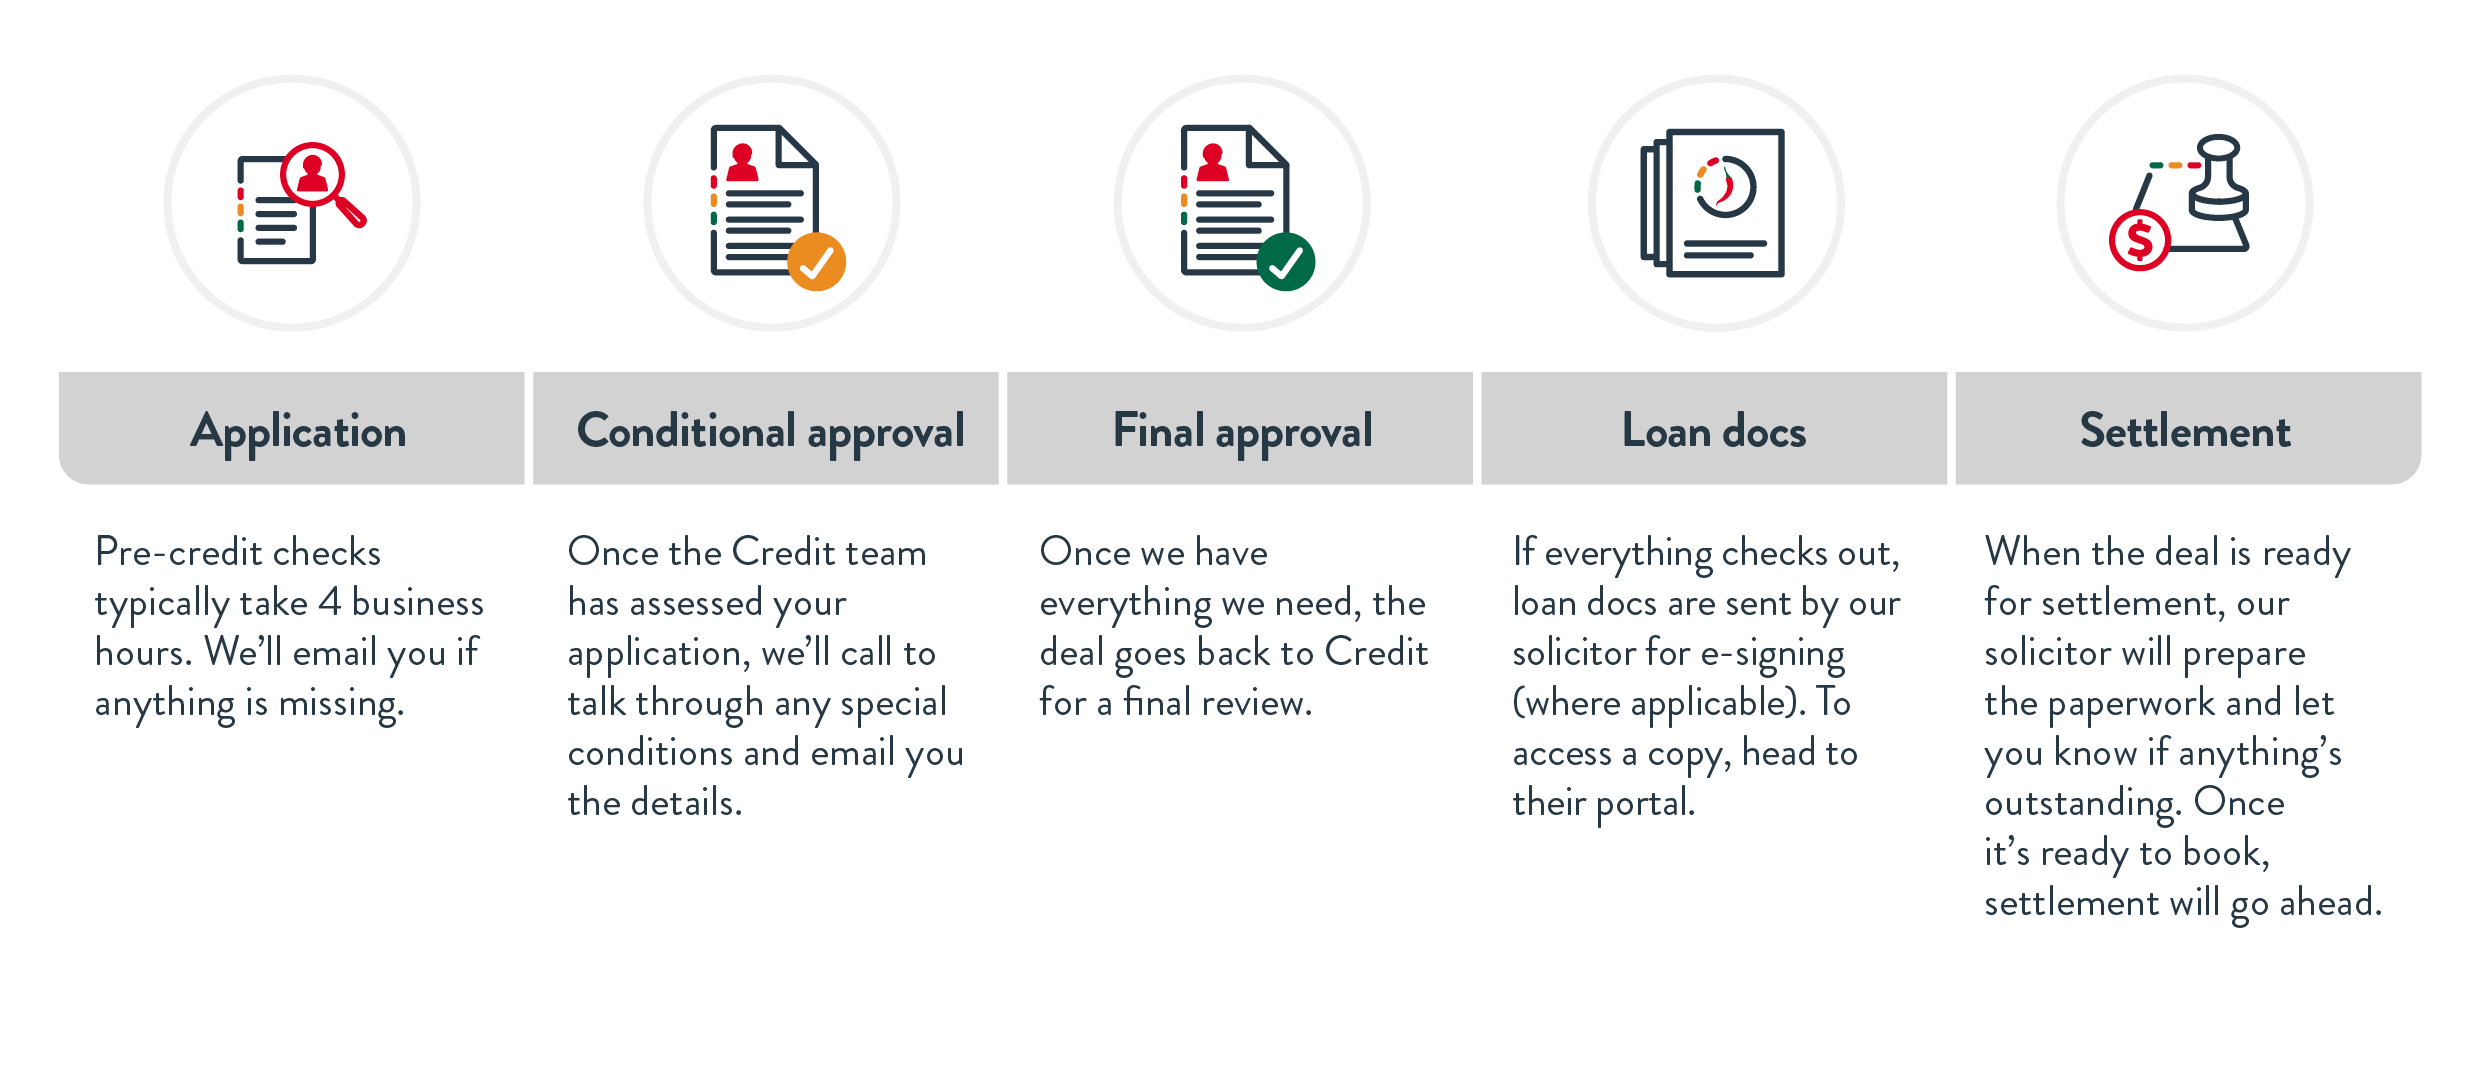
It’s easy to keep track of your client’s application with App Tracker, which gives you real time status updates and the ability to manage your conditions. Here’s an overview of what to expect from the process:
This section sets out key steps you may need to get to final approval.
Conditional approval stage: what to expect
If your client’s application is assessed and conditionally approved, we’ll send you an SMS and email letting you know. The email will contain things like the loan information and conditions. We’ll also share the details of your credit assessor so you can discuss questions you might have – with them directly.
At the conditional approval stage, you might need to:
What if you have to rework your deal?
You can email your request to advisersupport@peppermoney.co.nz.
Final approval stage: what to expect
If your client’s application is approved, we’ll send you an SMS and email letting you know. The email will contain all the information you need to progress to settlement.
At the final approval stage, we recommend reviewing settlement conditions. Here are some common ones you might need to satisfy:
- Make sure you send us a copy of the certificate of currency for the client’s home insurance.
- For refinances, make sure the other lender is ready to discharge the loan, and that we have the Discharge Authority on file.
- For purchases, ensure the conveyancer and client have organised the funds to complete before settlement (as we’re not a Non-Bank Deposit Taker (NBDT), we can’t hold funds to complete).
From there, we’ll engage our panel solicitors, check out our Adviser Hub for when your client’s solicitor can expect to receive their loan docs.
This section sets out key steps you may need to help the loan settle.
Getting your loan docs sorted
Loan documents are uploaded to the Propel portal, where your client’s solicitor can access them directly.
Once completed by your client and their solicitor, our panel solicitor will review the documents to make sure everything checks out. If it does, the loan will be made ready to book.
Settlement
Once the loan has settled, we’ll let you know by SMS and status updates through the solicitor portal.
To ensure settlement goes smoothly, make sure you satisfy all the conditions before the deal is ready to book. Here are some common ones:
- Make sure you send us a copy of the certificate of currency for the client’s home insurance.
- For refinances, make sure the other lender is ready to discharge the loan, and that we have the Discharge Authority on file.
- For purchases, ensure the conveyancer and client have organised the funds to complete before settlement (as we’re not a Non-Bank Deposit Taker (NBDT), we can’t hold funds to complete).
- If an Overseas Investment Office (OIO) consent is required, ensure you provide it to the conveyancer/solicitor before settlement.
Need to speak to someone? You can contact us at advisersupport@peppermoney.co.nz.
Post-settlement
We'll send your client information about what they can expect from us as their lender.
- 24 - 48hrs: If your client has opted in to digital communications, they'll receive a welcome email and a separate login email with instructions to set up their my.peppermoney online account. From there, they can view their account number, repayment amount and schedule, and manage their loan online.
- 3 business days: The Pepper Money team will call your client to talk through their loan and answer any questions they may have.
- 5 business days: If your client has opted to receive physical mail, we’ll send a welcome letter to their chosen address/es. They'll also receive a login email with instructions to set up their my.peppermoney online account.
You are protected by responsible lending laws. Because of these protections, the recommendations given to you about home loans are not regulated financial advice. This means that duties and requirements imposed on people who give financial advice do not apply to these recommendations. This includes a duty to comply with a code of conduct and a requirement to be licensed.
Information is correct as at 13 November 2026 and subject to change.
Applications are subject to responsible lending, credit assessment, eligibility criteria and lending limits. Terms, conditions fees and charges apply. Information provided is factual information only and is not intended to imply any recommendation about any financial product(s) or constitute tax advice. We recommend that clients obtain independent financial and/or tax advice.
© Pepper New Zealand Limited NZBN 9429031065153 | NZ Company Number 3416551
Important: this communication is for Pepper Money accredited financial advisers only – it is not to be provided to clients.


